CFTC Hypothetical Performance Disclosure
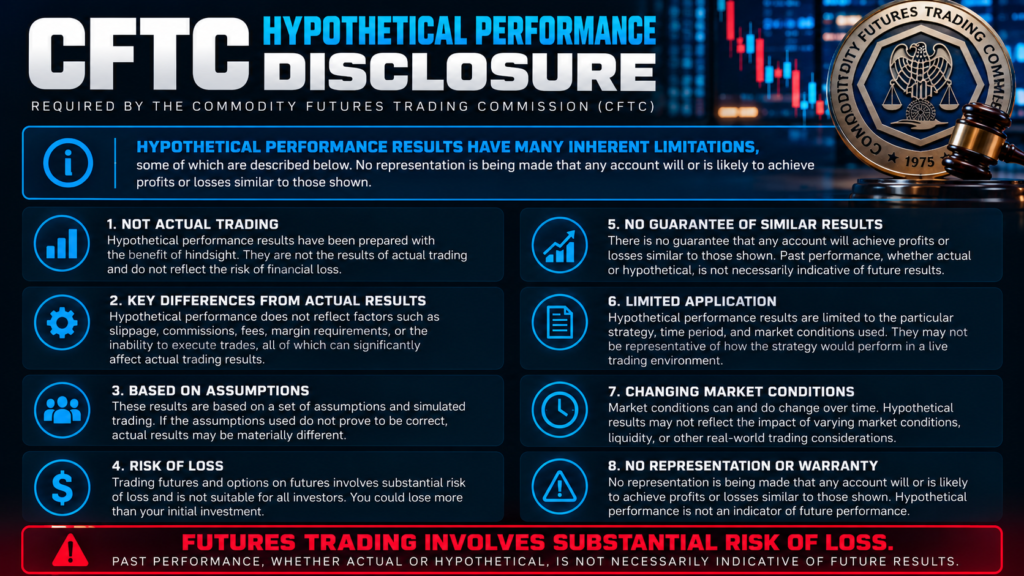
Backtests and simulated trading results are research tools, not evidence that an account will achieve the same returns in live markets. Understanding their limitations helps traders evaluate strategy demonstrations and performance claims.
The disclosure in CFTC Regulation 4.41
CFTC Regulation 4.41 addresses advertising by commodity pool operators, commodity trading advisors, and their principals. For covered hypothetical performance presentations, it requires a prescribed disclosure or an authorized futures-association alternative. The section applies even when the operator or advisor is exempt from registration.
Read the complete prescribed wording in 17 CFR § 4.41(b)(1). The explanation below is a summary, not a substitute for that wording.
What the disclosure means
Simulated results do not represent executed trades. They can misstate the effects of market conditions such as liquidity, and historical simulations benefit from hindsight. A hypothetical track record does not establish that any account will experience similar profits or losses.
Where the disclosure belongs
For non-oral presentations covered by the rule, the statement must be prominent and immediately next to the hypothetical performance. A separate disclosure page alone does not meet that placement requirement for results shown elsewhere.
Why a backtest can differ from live trading
Historical testing can favor settings selected after the outcome is known. Assumptions about order fills, slippage, fees, and available liquidity can materially change reported performance. Paper trading also cannot fully reproduce the financial pressure of real losses or the difficulty of following a strategy during a drawdown.
When assessing a simulation, ask which dates and instruments were tested, how costs and fills were modeled, and whether the strategy was evaluated on data excluded from its development. These questions help reveal what the results do—and do not—demonstrate.
Additional NFA requirements
For members and associates subject to the relevant NFA rules, additional restrictions govern hypothetical advertising, including disclosure of material assumptions, the prominence of disclaimers, and the treatment of actual results. Adding a disclaimer does not make an otherwise misleading presentation acceptable. See NFA Interpretive Notice 9025 for details and exceptions.
This article is educational information, not legal or investment advice. Applicable obligations depend on the activity, entity, and audience. Review the full regulation and applicable NFA rules when preparing performance materials.